
How to Calculate GST in India (Both Directions, Correctly)
Adding GST is easy. Removing it from an inclusive total is where the mistakes happen — and the intuitive method gives the wrong answer.
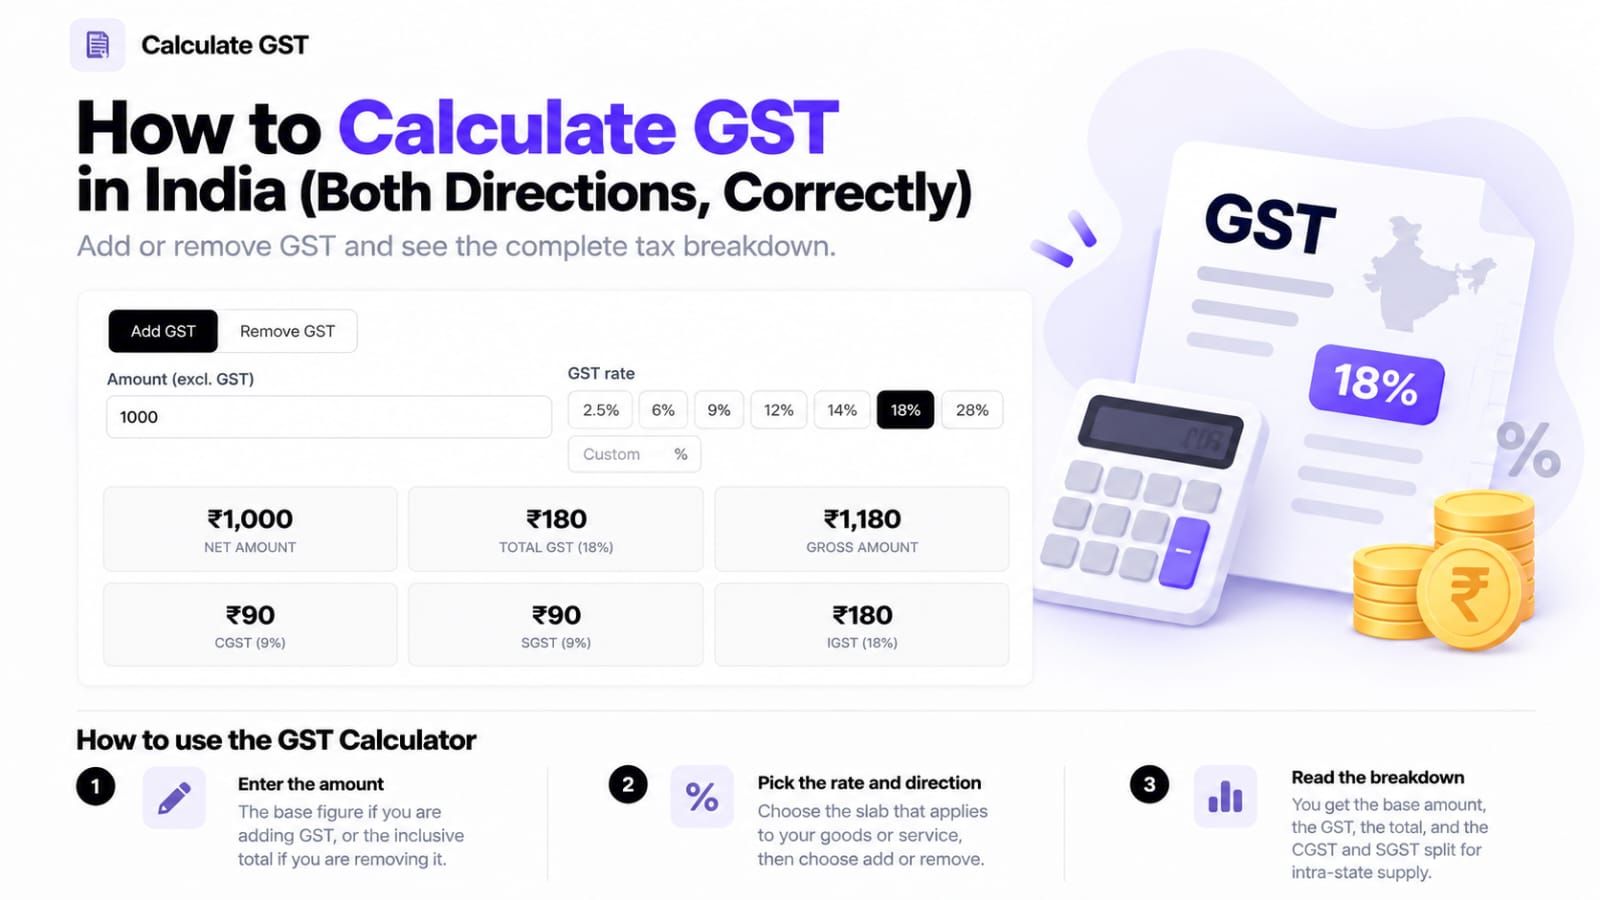
Table of Contents
GST arithmetic trips people up in one direction far more than the other, and the direction that goes wrong is the one small businesses need daily.
Adding GST: the easy direction
You have a base amount and need the total.
GST amount = base × rate / 100
Total      = base + GST amount
At 18% on ₹1,000: GST is ₹180, total is ₹1,180. Nothing surprising.
Removing GST: where it goes wrong
You have a tax-inclusive total and need to know how much of it was tax. The intuitive move is to subtract 18% from the total. That is wrong, and it is wrong in a way that looks plausible.
₹1,180 minus 18% gives ₹967.60. But we know the base was ₹1,000. The error is ₹32.40, and it grows with the amount.
The reason is that the 18% was calculated on the base, not on the total. Working backwards needs the reverse formula:
Base = inclusive total ÷ (1 + rate / 100)
GST  = inclusive total − base
₹1,180 ÷ 1.18 = ₹1,000. Correct.
The GST Calculator does both directions, so you can pick "remove GST" and enter the inclusive figure rather than remembering which formula applies.
The rates
The main rate framework uses 5% and 18%, with 40% for selected supplies. Exemptions, special rates, conditions and historical rates remain relevant. These percentages are not a classification table: check the HSN/SAC entry and the notification effective on the supply date. Exempt, nil-rated and zero-rated supplies have different legal treatment even when a simple calculation shows no tax.
If you are unsure which slab applies to what you sell, that is a question for your accountant or the official GST rate finder — not something any calculator can decide for you.
CGST, SGST and IGST
This is the part that confuses people reading their first invoice.
For a supply within a single state, GST splits evenly into two halves:
- CGST — the central government's share
- SGST — the state government's share
So 18% appears on the invoice as 9% CGST + 9% SGST. The customer pays 18% either way; the split is about who receives it.
For a supply across state lines, it is instead charged as a single IGST at the full rate — 18%, not split.
The total is identical. What changes is which boxes on the invoice are filled in, and the applicable treatment depends on place-of-supply rules and special cases, not the customer address alone. Use SGST or UTGST as applicable. Do not add IGST to CGST and SGST.
A worked example
Assume a taxable value of ₹50,000 and a verified total rate of 18% for a normal intra-state supply. This is an arithmetic example, not a classification of all services:
- GST: ₹50,000 × 0.18 = ₹9,000
- CGST: ₹4,500
- SGST: ₹4,500
- Invoice total: ₹59,000
For an inter-state supply under the applicable place-of-supply rules, the example instead shows IGST ₹9,000 and the same ₹59,000 total.
One caveat
Calculators produce arithmetic, not advice. Which slab applies, whether a supply is inter-state or intra-state, whether reverse charge applies, and what you can claim as input credit are all questions with real consequences. See our disclaimer, and check anything that matters with a qualified professional.
Verify the rate and your result
Use the GST Calculator, select Add GST or Remove GST, then choose the supply type. At an illustrative 5%, ₹1,000 becomes ₹1,050; at 40%, it becomes ₹1,400. A custom rate supports other verified or historical percentages. Do not enter only the CGST half as the total rate.
The result rounds to paise and allocates an odd paisa to one component. It excludes cess, composition schemes, input tax credit and special valuation. Compare your invoice system and statutory rounding requirements before relying on it.
Reviewed 4 November 2026 against the GST Council rate framework, time-of-supply FAQs and official notifications including 2026 amendments. Notification 02/2026 changes selected goods entries effective 1 November 2026; this illustrates why a calculator shortcut cannot replace checking classifications.